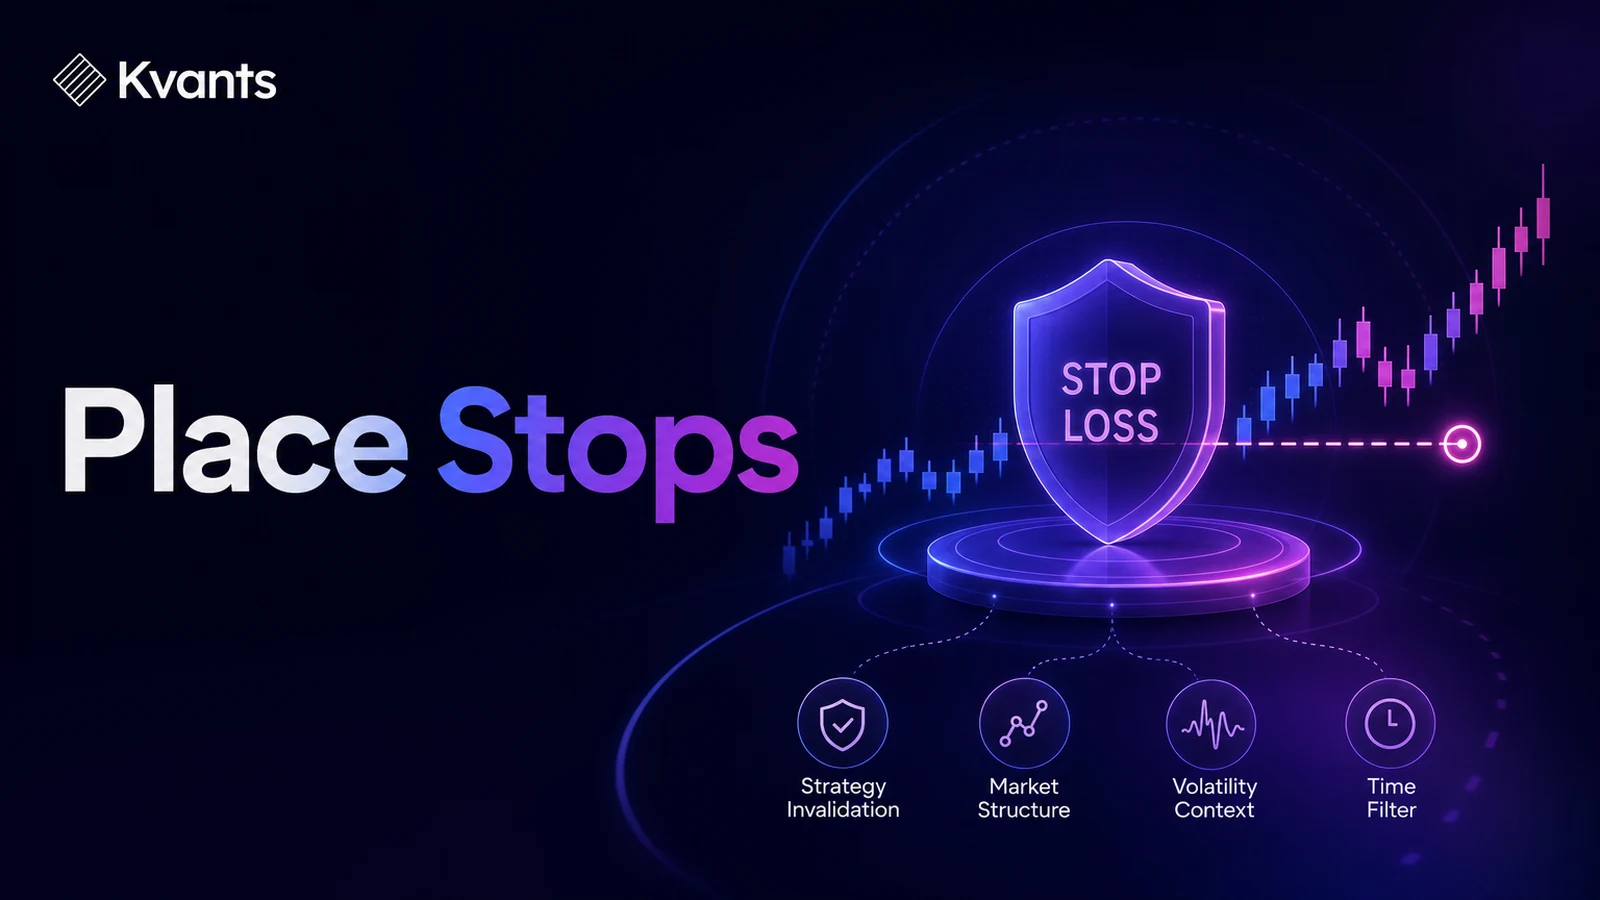
Learn how to place stop losses using strategy invalidation, market structure, volatility, and time—then size the trade and test the rule without hindsight.
Quick Answer
Place a stop where the original trade thesis becomes invalid, not at an arbitrary distance from the entry. Define that invalidation level using information available before entry, add a rule-based buffer if needed, and calculate position size from the resulting stop distance. The main limitation is that no stop method prevents gaps, slippage, or ordinary losing trades. A valid stop can still be triggered before price reverses, so the rule must be evaluated across many comparable trades rather than judged by one chart.
Key Takeaways
- Choose the stop rule from the setup’s logic before calculating position size.
- Structural stops fit price-pattern hypotheses; volatility stops fit strategies whose normal movement changes over time.
- Define the reference bar, calculation timing, buffer, trigger, and order behavior explicitly.
- Wider stops require smaller positions if account risk is held constant.
- Include fees, spread, slippage, gaps, and intrabar order sequencing when testing.
- Validate the complete entry-and-stop combination rather than optimizing the stop in isolation.
What a Stop Loss Is Supposed to Do
A stop loss defines when a position should be exited because its permitted loss has been reached or the reason for holding it no longer applies. It is part of the strategy—not an emergency feature added after entry.
Three values should remain separate:
- Invalidation level: The market level or condition that contradicts the trade thesis.
- Stop price: The price used to trigger an exit, potentially including a buffer around invalidation.
- Account risk: The amount the trader intends to lose if the exit occurs near the planned price.
Confusing these values creates backward logic. For example, a trader may decide to risk $100, choose 100 shares, and then place the stop $1 away simply because the arithmetic fits. That stop says nothing about the setup.
A better sequence is: define invalidation, calculate stop distance, and then derive position size. If the resulting size is impractical or below the market’s minimum order size, skip the trade or revise the strategy prospectively. Do not move the stop to justify a preferred position.
Stop Loss Placement Methods
Different strategies require different definitions of failure. The following methods are starting frameworks, not universal settings.
| Method | Example Rule | Best For | Main Limitation |
|---|---|---|---|
| Structural stop | Exit a long position below the confirmed swing low that supports the setup | Breakouts, pullbacks, and chart-structure strategies | Swing definitions can become subjective or use future information |
| Volatility stop | Exit a long position a specified ATR multiple below entry or a reference level | Markets with changing volatility | ATR settings and multipliers can be over-optimized |
| Fixed-distance stop | Exit at a fixed percentage, price distance, or number of ticks from entry | Simple strategies and instruments with stable behavior | Ignores changing structure and volatility |
| Time stop | Exit after a fixed number of bars if the expected move has not developed | Setups whose edge depends on rapid follow-through | Price may remain valid even when time expires |
A strategy can combine methods if the interaction is explicit. A breakout strategy might use a structural stop below the broken level plus a volatility buffer. A short-term momentum strategy might use a price stop and a time stop, exiting when either condition occurs first.
Complexity is not automatically better. Every additional condition creates another parameter, another timing decision, and another opportunity to fit historical noise.
A strategy laid out end to end in the Kvants editor.
A Step-by-Step Stop Placement Workflow
1. State why the trade should work
Write the hypothesis in one sentence. For example:
Enter long when price closes above a defined resistance level because the strategy expects continuation within the next five bars.
This sentence identifies two possible forms of invalidation: price can fall back below relevant structure, or continuation can fail to appear within five bars.
2. Define the invalidation reference mechanically
Replace visual language with observable rules. “Below support” is incomplete. Specify how support is calculated and when it becomes known.
A structural rule might say:
- Identify the lowest low of the five completed bars before the breakout bar.
- Freeze that value when the breakout signal closes.
- Place the long stop below that frozen low.
Freezing the level matters. Recalculating it after entry may silently move the stop or use bars unavailable when the decision was made.
3. Decide whether the level needs a buffer
Stops placed exactly at obvious highs, lows, or round numbers may be triggered by ordinary price variation. A buffer can be defined as:
- A fixed number of ticks
- A percentage of price
- A fraction of ATR
- The instrument’s expected spread plus a slippage allowance
The buffer should have an economic or execution rationale. Testing dozens of tiny variations and choosing the historical winner is parameter fitting, not evidence of a durable rule.
4. Specify the trigger and order behavior
“Exit at the stop” is not a complete simulation rule. Record:
- Whether the trigger uses the traded price, bid, ask, close, or intrabar high or low
- Whether the exit is represented as a stop-market or stop-limit order
- When the order becomes active
- What happens if price gaps through the stop
- How fees, spread, and slippage are modeled
A stop-market order prioritizes execution after activation, but the fill can be worse than the stop price. A stop-limit order controls the acceptable price range but may remain unfilled. Neither guarantees a specific loss.
5. Calculate position size from the stop
For a long trade:
stop distance = entry price − stop price
A cost-aware unit calculation is:
position size = floor(risk budget ÷ (stop distance + estimated cost per unit))
For leveraged or contract-based instruments, include the contract multiplier, tick value, and relevant currency conversion. Also check buying power, liquidity, minimum order size, and total exposure across correlated positions.
6. Define what can change after entry
Decide in advance whether the initial stop remains fixed, trails, moves to break-even, or is replaced by another exit. These are separate strategy rules.
Moving a stop farther away increases the planned loss and usually invalidates the original risk calculation. Moving it closer changes the trade’s outcome distribution and can turn normal price movement into premature exits. Either action should follow a tested rule rather than an emotional response.
7. Test the full strategy
Evaluate stop placement together with the entry, sizing model, profit exit, time exit, and trading costs. Useful outputs include:
- Expectancy after costs
- Maximum drawdown
- Win rate and average win-to-loss relationship
- Frequency and size of stop slippage
- Holding time
- Results across volatility regimes
- Sensitivity to nearby stop parameters
The goal is not to find the stop with the highest historical return. Look for a coherent rule whose behavior remains reasonably stable under realistic assumptions and unseen data.
Deploying a strategy to paper or live with a pre-flight gate.
Worked Example: A Structural Stop With a Volatility Buffer
Assume a hypothetical stock closes above a mechanically defined resistance level and produces a long entry at $50.60. The lowest low of the five completed pre-breakout bars is $49.80.
The strategy adds a $0.10 buffer below that structural level:
stop price = $49.80 − $0.10 = $49.70
The price risk per share is:
$50.60 − $49.70 = $0.90
Suppose the account is $20,000 and the trader’s predetermined risk budget for this setup is 0.5%, or $100. This percentage is illustrative, not a recommendation. If estimated spread, fees, and slippage equal $0.05 per share, the cost-aware risk is $0.95 per share:
position size = floor($100 ÷ $0.95) = 105 shares
The planned price risk is $94.50, while the remaining amount allows for estimated costs. Actual loss can exceed $100 if the market gaps below the stop or liquidity deteriorates.
Notice the sequence: the $49.70 stop came from strategy structure and a predefined buffer. The 105-share position came afterward. If the stop had been twice as far away, the position would need to be smaller to preserve the same risk budget.
Common Stop Placement Failure Modes
Choosing a distance because it produces a convenient position
This reverses the correct sequence. Position size should adapt to the strategy’s stop, not determine it.
Using hindsight to select the swing point
A swing low defined by future bars may not have been confirmed when the trade occurred. Backtests must enforce when each level becomes available.
Placing every stop at the same percentage
A fixed percentage is testable, but it may behave inconsistently when volatility changes. Compare it with a volatility-normalized or structural alternative rather than assuming simplicity makes it robust.
Treating the stop price as the guaranteed fill
Fast moves, gaps, spreads, latency, and limited liquidity can produce a worse exit. A backtest that always fills exactly at the trigger will understate risk.
Optimizing the stop independently
A tighter stop can raise apparent reward relative to initial risk while reducing the win rate. A wider stop may increase the win rate while enlarging losses and reducing position size. Judge the complete distribution after costs.
Moving to break-even without evidence
The entry price has psychological importance to the trader, but it is not automatically meaningful to the market. A break-even rule should specify when the move occurs and be tested like any other exit.
How to Test Stop Rules With Kvants
In Kvants Studio, a trader can describe entry, invalidation, buffer, sizing, and exit logic in plain English and turn it into editable, auditable strategy rules. This helps expose incomplete phrases such as “place the stop below support” before testing begins.
Backtests run on NautilusTrader’s event-driven engine, which is relevant when entry and stop orders can interact within the same bar. Traders can use constrained parameter sweeps to examine nearby ATR multipliers or buffer values, then apply walk-forward and crisis-stress validation rather than relying only on an optimized in-sample result.
Kvants supports stock and crypto research, Pine Script v6 export, and controlled paper or live workflows. The Kvants documentation provides additional guidance on strategy logic and exports, while the Kvants blog covers related validation concepts.
The tool does not decide what level is economically meaningful. That remains a research judgment, and more testing cannot rescue a vague or hindsight-dependent hypothesis.
Kvants audits that the engine runs the strategy you configured.
Frequently Asked Questions
Where should I place a stop loss?
Place it at a predefined price or condition that invalidates the trade thesis. Depending on the strategy, that may be beyond market structure, a volatility-adjusted distance from a reference level, or a time limit after entry.
Is an ATR stop better than a percentage stop?
Not universally. ATR adjusts to recent volatility, which can help across changing conditions. A percentage stop is simpler and may suit stable instruments or broad portfolio rules. Test each method with the same entries, costs, sizing logic, and validation periods.
Should a stop loss be placed below support?
Only if support is part of the long trade’s hypothesis. Define how support is identified, when it becomes known, and whether the stop sits directly below it or includes a buffer. “Below support” alone is not reproducible.
How much should I risk on one trade?
There is no suitable universal percentage. The amount should reflect account constraints, strategy drawdowns, losing-streak tolerance, liquidity, correlated exposure, and the possibility that actual losses exceed planned losses. Risk only capital you can afford to lose.
Should I move my stop to break-even?
Only under a predefined rule supported by testing. Moving to break-even can reduce some losses, but it can also exit trades during normal pullbacks. Compare its effect on expectancy, drawdown, holding time, and execution costs.
Can a stop loss guarantee my maximum loss?
No. Stop orders can fill beyond their trigger price during gaps, fast markets, or periods of poor liquidity. Stop-limit orders may not fill at all. Position sizing should include an allowance for execution uncertainty, while recognizing that extreme losses can exceed that estimate.
Risk Note
This article is educational and is not investment advice. Trading stocks and crypto involves substantial risk, and stop-loss orders cannot guarantee execution at a specific price or prevent losses. Backtested performance does not guarantee future results. Kvants is a research tool, not an investment adviser, and never guarantees performance.