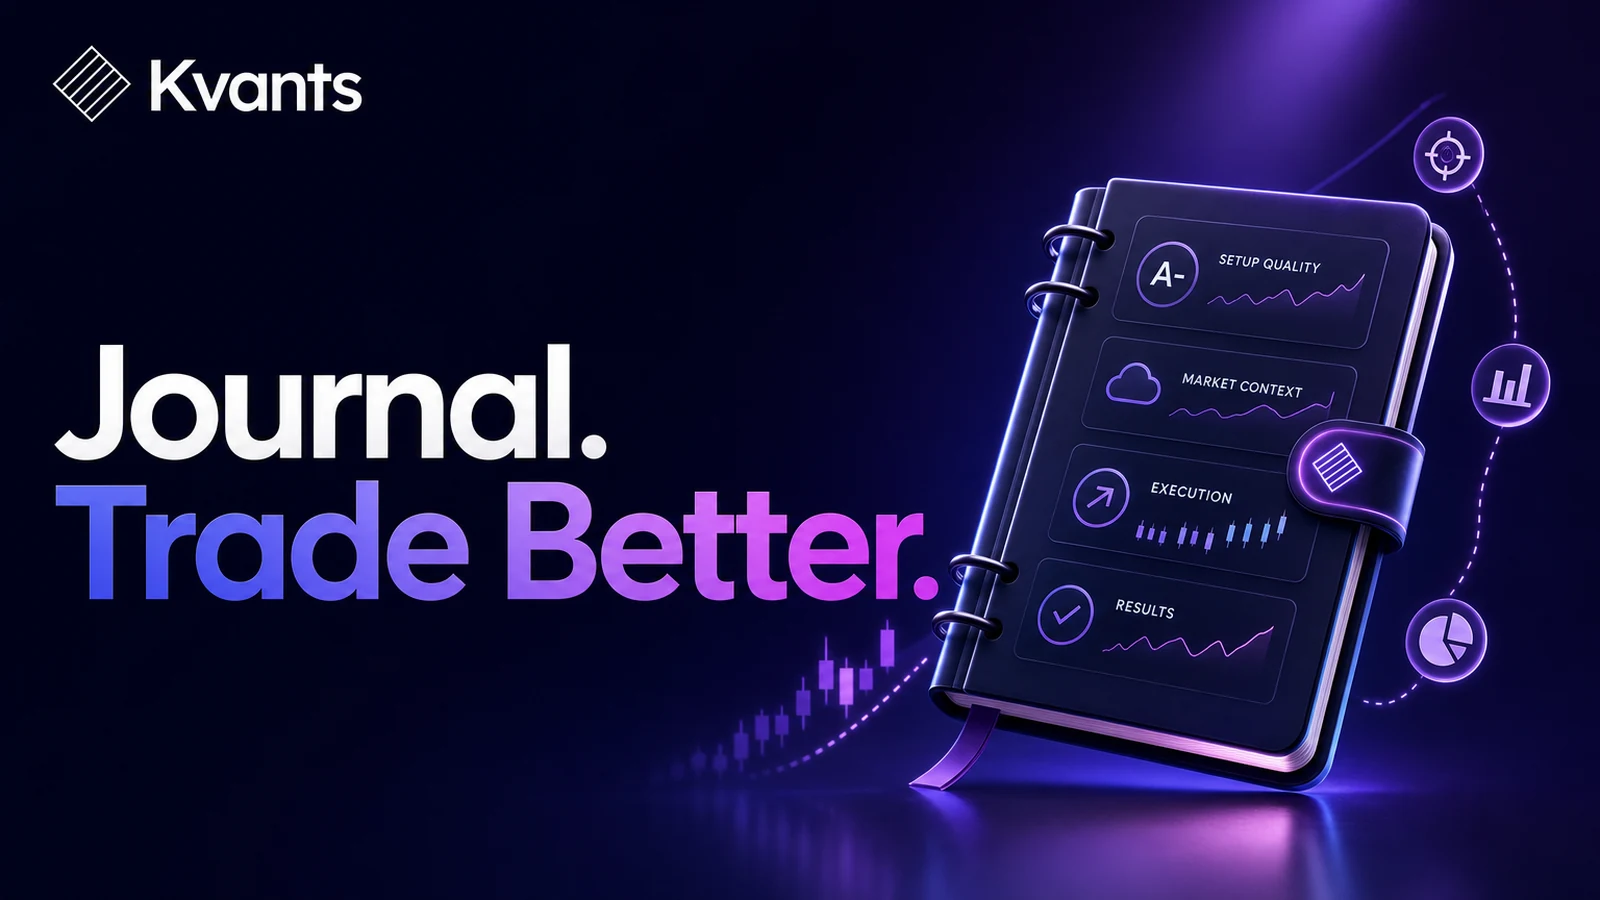
Build a stock trading journal that separates setup quality, market context, execution, and results, then review it systematically to find testable patterns.
Quick Answer
A useful stock trading journal records the setup, pre-trade thesis, planned risk, stock-specific context, executions, result in R, and whether each rule was followed. Review trades by setup first, then add one contextual variable such as sector alignment, catalyst, liquidity, or time of day.
The main limitation is evidence quality. A small, inconsistently tagged journal can suggest patterns but cannot establish that they are durable. Treat journal findings as hypotheses to investigate rather than conclusions to trade automatically.
Key Takeaways
- Separate setup quality, execution quality, and financial outcome.
- Record the thesis and invalidation condition before the outcome is known.
- Use predefined tags instead of inventing labels during each review.
- Measure results in R-multiples as well as dollars.
- Analyze the primary setup before adding contextual filters.
- Convert recurring journal observations into explicit research questions.
What a Stock Trading Journal Should Track
A journal should let you reconstruct what the market was doing, what you planned, what you executed, and how the trade ended. Keeping those layers separate prevents a good outcome from disguising a poor decision.
Trade identity and executions
Record the symbol, date, direction, entry and exit timestamps, prices, share quantity, fees, and order types. Preserve individual executions when scaling in or out rather than replacing them with an approximate average.
These fields establish what happened. They can also expose late entries, unexpected transaction costs, excessive scaling, and trades placed outside the intended session.
Setup and pre-trade thesis
Assign one primary setup label, such as opening-range breakout, pullback, gap continuation, or mean reversion. Define each label in a playbook so that two visually different trades do not receive the same tag without a clear reason.
Add a one-sentence thesis based on observable conditions. For example:
Price held above the opening range after a gap, while the stock’s sector remained stronger than the broad market.
“Looked strong” is not sufficiently precise. It cannot be evaluated consistently or converted into a testable rule.
Record the intended entry trigger, initial stop, invalidation condition, target logic, and expected holding period. These fields preserve the original plan before the result creates hindsight bias.
Planned and realized risk
Track planned dollar risk, initial stop distance, intended share size, actual share size, and the final result in R.
One R is the amount initially placed at risk if the planned stop is reached. If planned risk is $100, a $150 net gain is +1.5R and a $75 net loss is -0.75R. R-multiples make trades with different prices and position sizes easier to compare.
Do not assume planned risk and realized risk will match. Gaps, slippage, stop changes, partial exits, and unplanned additions can create a meaningful difference. That execution gap deserves its own field.
Stock-specific context
Generic notes often omit conditions that matter in stock trading. Useful fields can include:
- Sector or industry: Was the stock moving with or against its group?
- Liquidity category: Could the intended size reasonably be entered and exited?
- Relative activity: Was volume or range elevated compared with the stock’s own history?
- Catalyst: Earnings, guidance, company news, analyst action, macro event, or no identified catalyst.
- Gap context: Direction, approximate size, and relationship to prior reference levels.
- Market regime: Trending, range-bound, volatile, or quiet under predefined criteria.
- Session: Pre-market, regular session, or after-hours.
Only collect fields that support recurring questions. More data does not improve a journal if the fields are inconsistently completed or never reviewed.
Rule adherence and decision notes
Track entry, size, stop, and exit compliance separately. A single “followed plan” checkbox hides which part of the process failed.
Psychology notes should connect an emotion to an action. “Felt anxious” offers little direction. “Exited before the planned signal after two declining bars” identifies a decision that can be reviewed against the strategy rules.
Save a chart from before or near entry when practical, followed by a post-trade chart. Mark the planned trigger, stop, target, and important levels. A pre-trade image helps preserve information that was actually visible when the decision was made.
The Kvants trading terminal and market co-pilot.
A Step-by-Step Stock Trading Journal Review
1. Reconcile the raw records
Verify timestamps, quantities, fees, partial fills, and average prices. Resolve duplicated or missing executions before calculating statistics. Incorrect records can distort holding time, entry quality, risk, and net results.
2. Audit the process before the outcome
For every trade, ask:
- Did the trade qualify under the documented setup?
- Did entry occur after the required trigger?
- Was position size within the risk limit?
- Was the stop changed for a predefined reason?
- Did the exit follow the stated rule?
Classify trades as valid and well executed, valid but poorly executed, invalid with a gain, or invalid with a loss. An invalid trade does not become good execution because it made money.
3. Group results by primary setup
For each setup, review trade count, average and median R, win rate, average winner, average loser, drawdown, and rule-adherence rate. No single metric provides a complete diagnosis.
Keep rule versions separate. If the definition of a breakout changed during the review period, label the versions rather than treating every trade as an identical observation.
4. Add one contextual variable
After evaluating the setup alone, split it by one variable such as sector alignment, catalyst, market regime, liquidity, or time of day.
Avoid applying several filters simultaneously. A narrowly defined subgroup can look unusually strong or weak by chance, especially when it was discovered only after inspecting many combinations.
5. Measure execution gaps
Compare planned and actual entries, size, stops, and exits. Look for repeated behaviors such as entering before confirmation, moving stops, adding outside the sizing plan, or closing trades during ordinary price movement.
Measure the effect in R when possible. This helps distinguish a strategy issue from an execution issue. A sound setup entered too late may fail because the available reward no longer justified the remaining risk.
6. Choose one next action
End each review with a limited decision. You might collect more observations, stop taking a setup outside regular hours, enforce an existing entry rule, or investigate a specific context filter.
Record the effective date of any change. Otherwise, future analysis may combine trades governed by different rules.
A strategy laid out end to end in the Kvants editor.
Worked Example: Turning a Journal Pattern Into a Hypothesis
Imagine a trader reviews 36 long breakout trades. In this sample, trades taken when the stock’s sector was stronger than a broad-market benchmark had better average results than those taken without sector alignment.
That does not establish that sector alignment improves all breakout strategies. The sample may cover a narrow market environment, and the filter may have been selected after inspecting several variables.
A more defensible conclusion is:
Long breakout outcomes may differ when sector return over a defined lookback exceeds broad-market return over the same period.
That observation can become a research specification by defining:
- The breakout level and confirmation rule
- The sector benchmark assigned to each stock
- The relative-strength lookback
- When the signal becomes observable
- Entry and exit order timing
- Position sizing, fees, and slippage
The goal is not to prove the journal correct. It is to create a rule precise enough to challenge with broader evidence.
Common Stock Trading Journal Failure Modes
Recording only P&L
P&L describes the outcome, not the decision process. Without setup, context, risk, and adherence fields, you cannot separate a repeatable process from favorable chance.
Writing the thesis after the trade
Once the result is known, the chart often appears more predictable. Keep the pre-trade thesis separate from post-trade observations so the original reasoning remains auditable.
Using inconsistent tags
“Breakout,” “range break,” and “ORB” may describe overlapping or entirely different setups. Maintain a controlled tag list with a short definition for every approved label.
Changing several rules together
If the entry, stop, filter, and target change simultaneously, later results cannot show which adjustment mattered. Version the strategy and limit each revision to a clear research purpose.
Overfitting filters
A combination of symbol, weekday, hour, sector, and catalyst can create a tiny subgroup with impressive historical results. Treat findings from repeated filtering cautiously and test them on untouched data.
Confusing execution with strategy quality
Poor execution can damage a valid strategy, while disciplined execution cannot create an edge where none exists. Analyze rule quality and rule adherence independently.
From Journal Insight to Strategy Research
A journal documents real decisions and execution behavior. A backtest applies explicit rules repeatedly across historical data. The two tools answer different questions.
When a journal reveals a recurring observation, Kvants Studio can turn the plain-English idea into editable, auditable strategy logic. Traders can inspect the rules, use event-driven backtesting on NautilusTrader’s engine, explore parameter ranges, and perform walk-forward or crisis-stress validation.
For example, the sector-alignment hypothesis could become a stock strategy with defined relative-strength, breakout, timing, cost, and exit rules. Parameter sweeps can then show whether the result persists across nearby definitions or depends on one convenient threshold.
Testing still requires caution. Survivorship bias, corporate actions, incomplete data, unrealistic fills, and repeated experimentation can all distort a result. The practical purpose is to challenge a journal-derived hypothesis before adding it to a trading plan. Additional research workflows are available in the Kvants documentation and Kvants blog.
Configuring a backtest in Kvants Studio.
Frequently Asked Questions
Should I use a spreadsheet or dedicated trading journal?
Use the format you can maintain consistently and audit. A spreadsheet offers flexibility, while dedicated software may simplify imports and reports. In either case, preserve executions, control tag definitions, and keep pre-trade notes separate from post-trade analysis.
How often should I review my stock trading journal?
Check data quality and rule adherence after each session. Review setup-level patterns weekly or monthly depending on trading frequency. Avoid changing strategy rules in response to only a few recent trades.
How many tags should each trade have?
Use one primary setup tag and a limited set of predefined context and execution fields. Every tag should answer a recurring question. If a field is rarely completed or reviewed, remove or redesign it.
Should a rule-breaking trade with a gain count as a winner?
It is a positive financial outcome and a failed process trade. Preserve both classifications. Removing it from performance records distorts results, while calling it good execution rewards behavior that violated the plan.
Can a stock trading journal prove that a strategy has an edge?
No. It can reveal patterns, document behavior, and produce useful hypotheses. Stronger conclusions require explicit rules, broader historical testing, out-of-sample evaluation, realistic costs, and controlled forward observation.
Risk Note
This article is educational and is not investment advice. Stock trading involves risk, including possible loss of capital. Journal findings and backtests can be affected by incomplete data, bias, liquidity, costs, and changing market conditions. Backtested performance does not guarantee future results. Kvants is a research tool, not an investment adviser, and does not guarantee performance.